The short answer for Plan G vs High Deductible G: Plan G pays all your Medicare Part A and B cost-sharing except the annual Part B deductible. High Deductible Plan G has the same benefits but you pay the first $2,950 (2026) of covered costs before it pays, in exchange for a much lower premium.
If you are shopping for a Medicare Supplement plan, then you keep hearing that Plan G is the most popular option for higher coverage right now. But higher coverage also means higher premiums. Not everyone can afford or wants to pay higher premiums. This is especially true as Medicare Supplement premiums keep rising!
This is where High Deductible Plan G enters the conversation! People who still want the freedom of having a supplement plan, but need a more affordable option can consider High Deductible G. The “High Deductible” on this plan is not the same as a traditional high deductible on other medical plans. We break down the differences between Plan G and High Deductible Plan G in detail below, and explain how the High Deductible works.
What is a Medicare Supplement (Medigap)?
A Medicare Supplement, also called a Medigap plan, is a separate plan on top of Medicare that helps pay your portion of Medicare Part A and Part B expenses. There are several different standardized Medigap plans that are regulated by Medicare. These plans varying based on how much and which portions of your Medicare covered expenses they pay. In general, the more they pay, the higher the premiums.
Your costs with Medicare Part A and Part B include:
- Part A deductibles and Copays.
- Part B Deductible and 20% Coinsurance (without a maximum out-of-pocket spending cap)
- Part B excess charges
- The first 3 pints of blood
- All medical expenses while out of the country
What does Medicare Supplement Plan G Cover?
Plan G has the most coverage you can get with a Medicare supplement plan for anyone turning 65 after 2020. Plan G covers all your Medicare Part A and Part B charges, except your Part B deductible each year. After you meet your deductible, you will not pay any Medicare approved Part A or Part B charges when you seek care.
Plan G covers all the following expenses after your Part B deductible:
- Part A Deductible and coinsurance
- Part B 20% coinsurance and excess charges
- The first 3 pints of blood that Medicare doesn’t cover
- Emergency medical expenses up to $50,000 while out of the country (lifetime maximum)
What does High Deductible Plan G (HDG) cover and how does the deductible work?
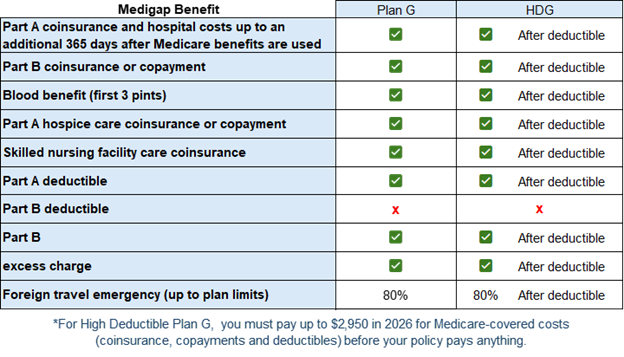
High-Deductible Plan G covers your portion of all the same Medicare costs as Plan G, but it doesn’t start paying those costs until after you reach the deductible. The deductible for this plan is $2,950 for 2026. This does not mean you are paying 100% of medical expenses until you reach $2,950 per year! This is where people get confused about how the deductible works.
Plan G versus HDG Comparison Table
How does the deductible work on High-Deductible Plan G?
On a High-Deductible G (HDG) plan, you pay the first $2,950 of your portion of Medicare Part A and Part B expenses. Medicare still pays 80% of Part B services after the Part B deductible is met each year. On a HDG plan, you cover the remaining 20% until the full HDG plan deductible is reached.
For Part A costs, if admitted to the hospital you pay the hospital deductible then Medicare pays the rest for the first 60 days. If you reach your HDG plan deductible between Part A and/or Part B, then your HDG plan pays 100% of your charges.
This is a good option for someone who wants the flexibility of a Medicare Supplement plan but doesn’t want a higher premium or doesn’t typically have a high usage of medical care.
Can I go from High Deductible Plan G to standard Plan G if I need more coverage later?
If you start with High Deductible Plan G and your health takes a turn, then you may not be able to pass underwriting to switch plans (unless you live in a state with a Birthday Rule). If you think you may have more health issues later in life, then this could be a deterrent from buying a High Deductible Plan G.
Depending on your state, you may have another option available with Innovative Plan G (Physicians Mutual). This is not a standardized plan to compare across the board, but it is worth noting if you are in a state where Physicians Mutual offers it.
What is Innovative Plan G by Physicians Mutual?
This company specific plan is Physicians Mutual’s rider on top of standard Plan G. This plan option has an introductory high-deductible on standard Plan G for the first 3 years at a lower premium price. After three years, the deductible disappears, the plan reverts to the standard Plan G, but you keep the same lower premium rating for as long as you hold the policy. Depending on when you enrolled, this may not be a full 3 years. It counts calendar years. So if you enrolled in an Innovative Plan G in November, then November and December count as the full first year. Just remember rates can and do go up every year no matter what plan you choose.
This is a great option for someone who doesn’t expect to have a lot of medical complications early on but may need full coverage later in retirement. Since this is not a standardized plan, you cannot get it in every state. See grid below for available states.
| Innovative Plan G State Availability | |
|---|---|
| Arizona | Nevada |
| Utah | Colorado |
| South Dakota | Nebraska |
| Oklahoma | Texas |
| Iowa | Louisiana |
| Wisconsin | Illinois |
| Tennessee | Mississippi |
| Indiana | Alabama |
| Ohio | Pennsylvania |
| North Carolina | South Carolina |
Which Medicare Supplement plan is best for me?
Choosing between Plan G and High Deductible Plan G comes down to balancing your budget today against your coverage needs down the road. Standard Plan G offers predictable costs at a higher premium, while High Deductible Plan G trades a higher deductible for significantly lower premiums—making it a smart choice if you’re healthy, budget-conscious, and comfortable setting aside funds to cover costs until that deductible is met. If you need more help comparing plan, reach out to one of our friendly, licensed agents.
Frequently Asked Questions
Both plans cover the same Medicare Part A and Part B costs, but differ in when they start paying. Standard Plan G pays everything after you meet your annual Part B deductible. High-Deductible Plan G (HDG) doesn’t start paying until you’ve paid $2,950 (2026) of your Medicare cost-sharing, in exchange for a lower monthly premium.
The High-Deductible Plan G deductible is $2,950 for 2026. Once you reach it, the plan pays 100% of your covered Medicare Part A and Part B cost-sharing for the rest of the year.
No. This is the most common misunderstanding. Medicare still pays its share (80% of Part B services after the Part B deductible), and you pay only your portion until those out-of-pocket costs total $2,950. Once you reach that amount, HDG pays the rest.
Example: Leslie has High-Deductible Plan G (HDG). She recently visited a specialist and had labs completed. The bills for her doctor’s visit and labs total $500. She has already met her Part B deductible for the year, but she has not met her HDG deductible. This means her portion of these Part B charges will be $100 (20%). Once she meets her HDG deductible, she would pay $0 for Medicare charges.
After you pay your annual Part B deductible, Plan G covers:
Part A deductible and coinsurance
Part B 20% coinsurance and excess charges
The first 3 pints of blood
Emergency medical care abroad, up to $50,000 (lifetime maximum)
HDG covers the same benefits as standard Plan G, but only after you’ve paid the $2,950 deductible. Until then, you pay your share of Part A and Part B costs yourself.
It can be, if you’re healthy, don’t use much medical care, and can comfortably set aside money to cover costs up to the deductible. It’s a good fit for people who want the flexibility of a Medicare Supplement plan without a higher premium. It may not be a good fit if you expect heavy medical use.
People who expect more health problems later in life should think twice before deciding on High-Deductible Plan G. If your health declines, you may not be able to pass medical underwriting to switch to standard Plan G, unless you live in a state with a Birthday Rule.
Possibly, but it isn’t guaranteed. In most states you must pass underwriting, and a health change could block the switch. States with a Birthday Rule are the exception.
Innovative Plan G is a company-specific option (not a standardized plan) that starts with a high deductible on standard Plan G for the first three years at a lower premium. After that, the deductible goes away and the plan becomes standard Plan G, and you keep the lower premium rating for as long as you hold the policy. It’s available only in some states.
They count as calendar years, so your first year may be shorter. For instance, if you enroll at the end of the year, it still counts as a full year.
Hi, My name is Butterfly. I have been a licensed agent for over 10 years. I am contracted and certified to assist Medicare beneficiaries through the Medicare process. I specialized in educating the public about Medicare enrollment rules, timelines, and coverage options. My goals is to help you understand your options and help you avoid common enrollment mistakes that can lead to penalties or gaps in coverage.